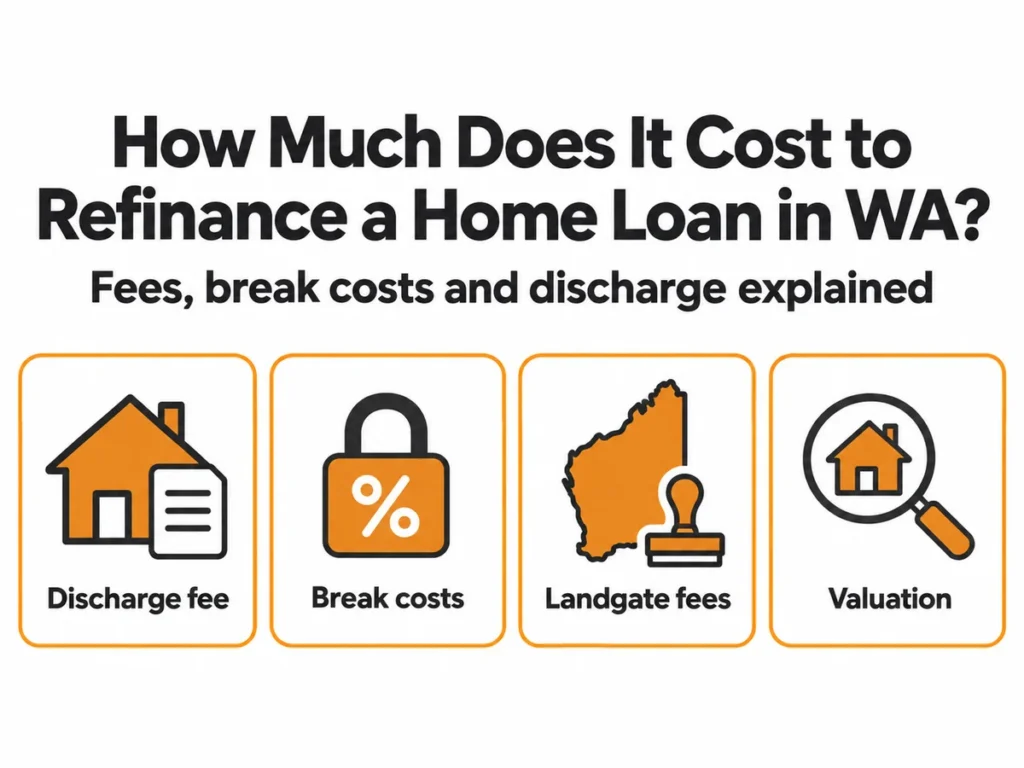
If you have been quoted a lower rate elsewhere, the first question most Perth homeowners ask is how much the switch itself will cost. The honest answer is that it depends on your current loan, but the individual costs are knowable in advance, and most of them are published. This guide sets out every cost that can apply when you refinance a home loan in Western Australia, which ones are fixed government charges and which ones vary by lender, and how to work out whether a refinance would pay for itself.
In short: the government side of a Western Australian refinance is modest and predictable. Landgate charges $225.10 to register the discharge of your old mortgage and $225.10 to register the new one (2026-27 schedule, effective 1 July 2026), and the PEXA electronic settlement fees are under $100 combined for a single-title refinance. The lender side is where the range opens up. A discharge fee from your current lender, any application or valuation fee from the new lender, and, if you are on a fixed rate, a break cost that can run from nothing to several thousand dollars. If your new loan would be above 80% of the property value, lenders mortgage insurance may be charged again. Total costs on a straightforward variable-rate refinance commonly land in the range of approximately $700 to $1,500 before any break cost, but every figure below should be checked against your own loan contract and a written quote.
The Government Charges That Apply in Western Australia
These are set by Landgate and by PEXA, the electronic settlement platform that Western Australian lenders and settlement agents use. They do not change from lender to lender.
- Landgate discharge of mortgage: $225.10 per mortgage, to remove the outgoing lender from your certificate of title.
- Landgate registration of mortgage: $225.10, to register the incoming lender’s mortgage. Landgate regulated fees are not subject to GST.
- PEXA fees: for Western Australia from 1 July 2026, a discharge of mortgage on a single title is $27.39 and a new mortgage is $55.99, both including GST. PEXA also lists a combined “Mortgage Express Refinance” transaction at $74.14 for a single title. Your lender or settlement agent normally passes these through.
Western Australia does not charge transfer duty on a refinance where the owners on the title stay the same. Duty is a tax, so confirm your own position with RevenueWA or your settlement agent if anything about ownership is changing at the same time, for example adding or removing a partner from the title.
Source: Landgate land transaction fees and PEXA Western Australia pricing, both current at 18 September 2026. Landgate reviews its fees each July, so check the current schedule if you are reading this later.
What Your Current Lender May Charge to Let You Go
Most home loan contracts include a discharge fee, sometimes called a settlement or termination fee, that covers the lender’s administration in preparing the discharge documents. Exit fees on variable loans taken out after 1 July 2011 were banned nationally, but a discharge fee is a different item and is still permitted. In our experience these commonly sit somewhere between approximately $150 and $400, and the exact figure is printed in your loan contract or your most recent statement.
If you have a package loan with an annual fee, check whether that fee has been charged for the current year. It is not usually refunded when you leave.
Break Costs on Fixed Rate Loans
This is the cost that catches people out. When you fix a rate, the lender locks in its own funding for that term. If you repay the loan early, the lender may recover the difference between what it locked in and what the same money is worth to it now. That difference is the break cost, and it can be zero, or it can be several thousand dollars, depending on three things:
- how much of the fixed term is left,
- the size of the fixed portion of your loan, and
- which direction wholesale rates have moved since you fixed. If market rates have fallen since you fixed, the break cost tends to be larger. If they have risen, it may be small or nil.
Lenders calculate break costs on the day, and the figure moves with the market. The only reliable way to know yours is to ask your current lender for a written break cost quote before you commit to anything. Most will provide one on request, and a broker will normally ask for this as the first step in any fixed-rate refinance conversation. Our guide to fixed vs variable rates in Perth covers how fixed terms work in more detail.
What the New Lender May Charge to Take You On
These vary widely and are the costs most open to comparison:
- Application or establishment fee: anywhere from nil to approximately $600 or more. Many lenders waive it for refinances, and some run promotional periods where it is removed entirely.
- Valuation fee: often absorbed by the lender, but some charge approximately $200 to $600 depending on the property and the type of valuation ordered.
- Settlement or legal fee: some lenders charge a small fee for their own settlement handling, separate from the PEXA and Landgate charges above.
- Ongoing fees: a monthly account fee or an annual package fee (commonly around $395 a year on packaged products) is not a refinancing cost as such, but it changes the comparison. A slightly lower rate with a $395 annual fee attached may cost more over time than a marginally higher rate with none.
Lenders Mortgage Insurance: The Cost Most People Forget
If your new loan would be more than 80% of the lender’s valuation of your property, the new lender may require lenders mortgage insurance (LMI). LMI protects the lender, not you, and it is not transferable between lenders. Any LMI you paid on your original loan stays with that loan.
This matters in Perth right now because valuations do not always keep pace with what owners believe their home is worth. If you bought with a 10% or 15% deposit in the last few years and the valuation comes in conservatively, a refinance may push you back above the 80% line and trigger a fresh LMI premium that can run into the thousands. Our article on lenders mortgage insurance in Perth explains how the premium is worked out.
A Worked Example of the Break-Even Calculation
This example is hypothetical and illustrative only. It uses round figures and assumed fees. Actual costs depend on your loan contract, your lender’s current fee schedule and the valuation.
A Perth homeowner has approximately $600,000 owing on a variable-rate loan. The costs of refinancing to another lender might look like this:
- Landgate discharge and new mortgage registration: $450.20
- PEXA refinance transaction: approximately $75
- Current lender discharge fee: approximately $350
- New lender application and valuation fees: waived in this example
- Break cost: nil, because the loan is variable
- Total: approximately $875
If the new loan’s interest rate were 0.40 percentage points lower than the current one, the interest saving in the first year would be roughly $2,400 on a $600,000 balance, before any change in fees or repayments. Dividing the total switching cost by the monthly interest saving gives a break-even point of around four to five months. Add a $2,000 fixed-rate break cost to the same scenario and the break-even stretches to roughly 14 to 15 months.
The point of the exercise is not the result. It is that the calculation can be done before you apply, with real figures from your own lender, so the decision is made on numbers rather than on a headline rate. ASIC’s MoneySmart has a free mortgage switching calculator that runs this comparison.
Costs That Are Not Really Costs
Two things often get counted as refinancing costs and are not:
Cashback offers. Some lenders offer a cash payment on refinance. It offsets your switching costs, but it usually comes with conditions on minimum loan size, loan-to-value ratio and how long you stay. Treat it as one input in the comparison, not the reason to move.
Time. A refinance in Western Australia typically takes two to six weeks from application to settlement, depending on how quickly documents and the valuation come through. There is paperwork involved, and our guide to switching your home loan without the stress walks through the process step by step.
How a Broker Approaches the Cost Question
When a Perth homeowner asks us whether refinancing makes sense, the first things we gather are the current loan contract, the most recent statement and, for fixed loans, a written break cost quote. From there the comparison is built on total cost over the period you actually expect to hold the loan, not on the advertised rate alone. Sometimes the answer is that the costs outweigh the gain for now, and our article on when to refinance covers the situations where a review tends to be worthwhile. Which path suits you depends on your circumstances.
Frequently Asked Questions
How much does it cost to refinance a home loan in WA?
The government charges are fixed: $225.10 each for the Landgate discharge and new mortgage registration, plus PEXA fees of under $100 for a single title. Lender fees vary. A straightforward variable-rate refinance commonly totals approximately $700 to $1,500 before any fixed-rate break cost or lenders mortgage insurance.
Do I pay stamp duty when I refinance in Western Australia?
Generally no. Western Australia does not charge transfer duty on a refinance where the owners on the title do not change. If ownership is changing at the same time, confirm the position with RevenueWA or your settlement agent, as duty is a tax matter.
How do I find out my fixed rate break cost?
Ask your current lender for a written break cost quote. The figure is calculated on the day and moves with wholesale interest rates, so a quote is only indicative until the loan is actually repaid.
Will I have to pay lenders mortgage insurance again if I refinance?
Possibly, if the new loan is above 80% of the new lender’s valuation. LMI is not transferable, so any premium paid on the original loan does not carry across.
Are there any hidden costs of refinancing?
The costs are all disclosed, but some are easy to miss: a discharge fee in your existing contract, an annual package fee on the new loan, and the possibility of a conservative valuation pushing you into LMI territory. A written quote for each item before you apply removes the surprises.
Want the Real Numbers for Your Loan?
If you would like to know what a refinance would actually cost in your situation, our brokers can gather the break cost quote, compare total costs across our lender panel and set out the break-even for you. Read about refinancing with Strategic Mortgages Perth or book a free, no-obligation chat.
Disclaimer: The information provided in this article is general in nature and does not constitute financial, tax, or legal advice. Individual circumstances vary. The examples used in this article are illustrative only, and actual outcomes will depend on your specific loan terms, interest rates and financial situation. Government fees are current as at 18 September 2026 and are subject to change. We recommend consulting with qualified professionals before making financial decisions.